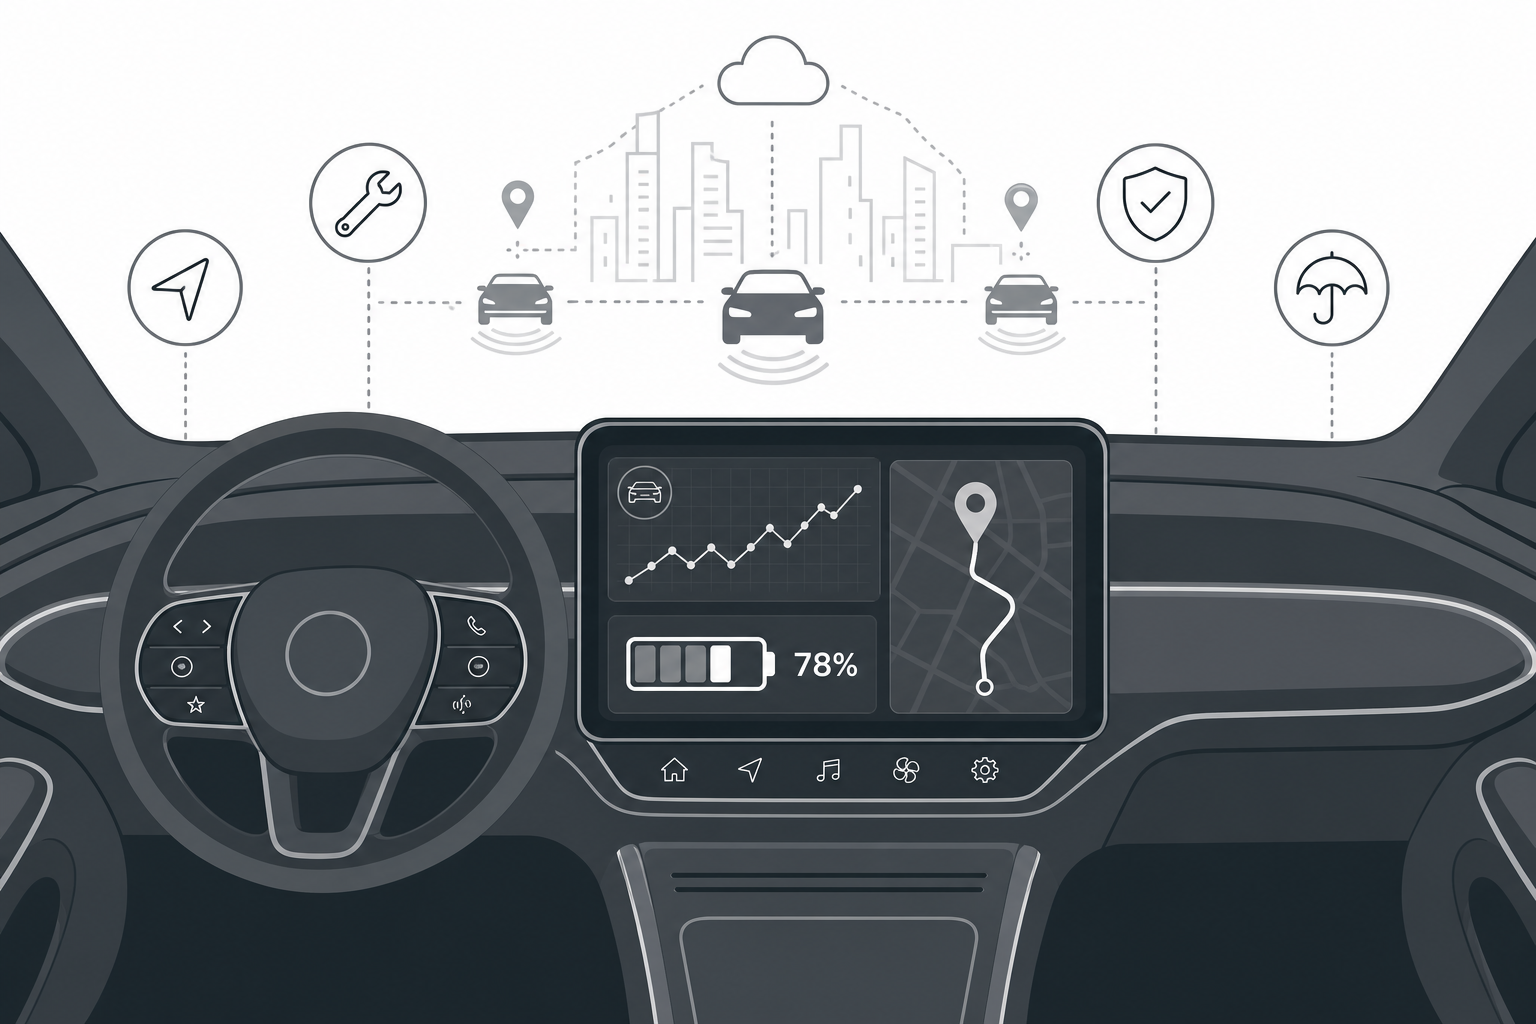
Vehicles are no longer just transportation machines — they are data-generating platforms. Every trip produces information on location, speed, braking patterns, battery state, and component health, and that data carries significant commercial value across insurance, fleet operations, urban planning, and digital services. As automakers, insurers, and technology providers work out how to capture that value, automotive data monetization has moved from a niche consideration to a mainstream business priority.
The global market for automotive data monetization was valued at $643.5 million in 2025 and is forecast to reach $1,692.0 million by 2031, expanding at a CAGR of 17.9% over the period 2026–2031. That trajectory reflects not just the growing number of connected vehicles on the road, but the maturing commercial infrastructure around them — subscription services, API platforms, AI-driven analytics, and data licensing arrangements that transform raw sensor output into recurring revenue.
The companies shaping this market range from established mapping and location intelligence providers to specialized API platforms and AI-native startups. The following sections profile the ten most prominent players and examine where the market's growth is concentrated.
Market Context: Segments and Regional Leadership
Among the deployment models, cloud infrastructure dominates, accounting for $444.7 million in 2025 — approximately 69.1% of the global market — with a CAGR of 18.8% through 2031. The scale of data generated by connected vehicles makes cloud processing a near-necessity for most commercial applications. On-premises infrastructure holds the remaining share, growing at 15.7% as data privacy concerns and regulatory requirements push some operators toward retaining direct control over vehicle and customer data. On the monetization model side, indirect monetization leads at $391.9 million — driven by fleet analytics, predictive maintenance, and usage-based insurance — while direct monetization, at $251.6 million, is growing faster at 19.5% CAGR and is expected to reach $718.2 million by 2031 on the strength of subscription services, in-vehicle commerce, and OTA feature unlocking.
By application, fleet management and optimization is the largest segment at $244.9 million, while predictive maintenance is the fastest-growing at a 21.4% CAGR, reflecting accelerating investment in AI-driven diagnostics. Regionally, North America leads with 37.4% of global market share in 2025 and a CAGR of 15.8% through 2031, underpinned by high telematics penetration, strong connected vehicle technology providers, and rising software-defined vehicle investment. Asia-Pacific is the fastest-growing region at 21.5% CAGR, driven by expanding connected car services in markets including India and Singapore. Europe follows at 18.9% CAGR, supported by regulatory frameworks for digital mobility and growing connected EV deployment.
The Top 10 Companies in the Global Market for Automotive Data Monetization
1. HERE
• Headquarters: Eindhoven, Netherlands
• Founded: 1985
• Employees: 6,400
• Focus: Maps and location data, EV routing, fleet routing, automated driving, digital cockpit, location analytics, AI-powered navigation for software-defined vehicles
HERE is one of the longest-established names in location intelligence, with a portfolio spanning maps and data, asset tracking, professional navigation, and automated driving. In 2026, the company launched an AI-powered product portfolio targeting software-defined vehicles, integrating location data, AI, and real-time analytics to support advanced navigation and personalized in-vehicle services. A 2026 partnership with Kotei focuses on AI-native navigation for the SDV sector, while a 2024 expansion with what3words added precise three-word addressing through HERE's APIs.
2. ARITY
• Headquarters: Dallas, Texas, U.S.
• Founded: 2014
• Focus: Mobility data and analytics, usage-based insurance, driving behavior targeting, fleet management, public sector transportation analytics, retail mobility insights
Arity operates a large-scale mobility analytics platform built around driving behavior data, serving insurers, fleet operators, transportation agencies, and mobility providers. In 2024, it expanded its partnership with Iteris to integrate driving behavior datasets into the ClearMobility Platform for traffic and roadway performance insights. In September 2025, it launched Geosight, a ZIP code-level driving behavior product for territorial insurance pricing. Arity also made its vehicle miles traveled data available through the Google Cloud Marketplace to support insurance and mobility analytics.
3. AUTODATA LTD.
• Headquarters: Leeds, U.K.
• Founded: 1972
• Focus: Automotive technical data, OEM data for 43,000-plus models, motorcycle diagnostics, EV and hybrid vehicle technical support, predictive maintenance, fleet management, aftermarket solutions
Autodata Ltd., operating within the Solera group, is a long-standing provider of automotive technical data to workshops and fleet operators across the aftermarket. Its current strategic expansion covers EV and hybrid vehicle support through integration with HEVRA, enabling independent workshops to service electrified vehicles. In December 2025, AutoData Middle East launched AutoData Analytics, a predictive intelligence platform for manufacturers, dealers, financiers, and insurers across the GCC region. A 2026 partnership with Seez brought AI-driven residual value forecasting and automotive intelligence to the MENA region.
4. CARUSO
• Headquarters: Koln, Germany
• Founded: 2017
• Focus: Fleet data, insurance data, workshop and roadside assistance data, vehicle diagnostics, vehicle status and driving behavior analytics, Dataplace Platform
CARUSO operates the Dataplace Platform, which standardizes and delivers in-vehicle data to fleet managers, insurers, independent repair workshops, and roadside assistance providers. The company uses Vehicle Identification Number-based personalized data delivery and maintains full GDPR compliance across its operations. In 2026, CARUSO joined the Communication Association to advance collaboration in the automotive aftermarket, focusing on improving standardized data access for independent repairers while meeting evolving cybersecurity and data regulations. It continues to expand the Dataplace Platform's use cases for connected mobility.
5. CEREBRUMX
• Headquarters: Novi, Michigan, U.S.
• Founded: 2020
• Focus: AI-driven automotive data monetization, fleet management, connected mobility, EV data and charging infrastructure, usage-based insurance, predictive maintenance, smart cities, OEM data insights
CEREBRUMX is organized around its Augmented Deep Learning Platform (ADLP), launched in 2024, which collects and standardizes real-time data from millions of connected vehicles to power analytics, data marketplaces, and predictive insights for OEMs and enterprises. Product lines include FleetConnect, MobilityConnect, and EVConnect. The company partnered with Onward Fleet Solutions to enhance AI-driven fleet telematics and counts LG Technology Ventures, BlackBerry, Pioneer, and Cerence among its strategic partners.
6. HIGH MOBILITY
• Headquarters: Berlin, Germany
• Founded: 2013
• Focus: Connected-car data platform, fleet management, usage-based insurance, EV charging, predictive maintenance, stolen vehicle recovery, mileage tracking, crash management, residual value monitoring
High Mobility provides a unified API platform that aggregates connected vehicle data from approximately 30 automotive company partners using official OEM data sources. In 2024, it integrated Volvo Cars data into its platform and extended its partnership with Volkswagen Group to deliver live data across multiple brands through a single standardized API. A further 2024 partnership with flespi combines High Mobility's OEM data access with flespi's IoT data processing and streaming capabilities, supporting real-time vehicle data utilization across fleet and mobility applications.
7. INRIX
• Headquarters: Kirkland, Washington, U.S.
• Founded: 2004
• Focus: Mobility and traffic analytics, real-time traffic management, parking solutions, fleet management, AI-driven road safety, geospatial data insights, EV charging data, drive time and location analytics
INRIX operates an on-demand mobility analytics platform used by cities, transportation agencies, and private sector operators to manage traffic, improve road safety, and optimize fleet operations. In 2026, the company launched Compass AI, a generative AI platform that helps cities identify and address roadway safety risks using a transportation data lake. That same year, INRIX expanded its partnership with the Texas Department of Transportation to deliver next-generation traffic and safety intelligence. A 2025 partnership with Western Systems combined INRIX's analytics with transportation infrastructure expertise for intelligent traffic management.
8. MOBITO
• Headquarters: Brussels, Belgium
• Founded: 2020
• Focus: Probe data, origin-destination data, driving events and standstill events data, road health data, usage-based insurance, fleet management, traffic optimization, EV network planning, road maintenance and safety monitoring
Mobito aggregates anonymized mobility and vehicle data from over 8 million connected vehicles across multiple brands and regions, making it available for applications in traffic optimization, road maintenance, EV infrastructure planning, and safety monitoring. The company serves cities, infrastructure operators, and commercial businesses, and supports automotive R&D teams developing behavior-based driver profiles for vehicle design, ADAS feature development, and insurance modeling. Its data-as-a-service approach is oriented toward scalable, multi-application use of standardized vehicle-generated data.
9. MOTORQ INC.
• Headquarters: San Francisco, California, U.S.
• Founded: 2017
• Focus: Connected vehicle intelligence, fleet management, usage-based insurance data, predictive maintenance, lender and rental solutions, dealership solutions, AI-powered vehicle data analytics via Motorq Fuse
Motorq focuses on converting connected vehicle data from major OEMs into decision-ready insights without additional hardware. In 2026, it launched the Fuse platform, which integrates data from multiple OEM and telematics sources using AI and cloud analytics to serve fleet, insurance, and mobility applications. A 2025 partnership with Volvo Cars delivers embedded vehicle data to fleets and dealerships across the U.S. and Europe. In March 2026, Motorq partnered with Snowflake to reduce OEM data delivery latency from hours to seconds. Its OEM partner network includes GM, Ford, BMW, Hyundai, Toyota, Stellantis, Volkswagen, Mercedes, and Rivian.
10. SMARTCAR
• Headquarters: Mountain View, California, U.S.
• Founded: 2015
• Focus: Car API platform, EV charging management, fleet tracking, usage-based insurance data, predictive maintenance data, vehicle signals and commands, OAuth vehicle data access via Smartcar Connect
Smartcar provides a unified API platform that gives developers and businesses standardized access to connected vehicle data across 46 automotive brands in 33 countries, reaching more than 177 million connected vehicles through a single integration. Its OEM partnerships include Volvo Cars, BMW Group, Mercedes-Benz, Ford, and Wallbox. Use cases span EV charging and energy management, fleet tracking, usage-based insurance, and predictive maintenance. Smartcar Connect provides OAuth-based vehicle data authorization, enabling compliant and secure data access for third-party applications at scale.
Conclusion
The ten companies profiled here reflect the variety of approaches taking shape in automotive data monetization. Some, like HERE and INRIX, bring decades of location and mobility intelligence to bear on new connected vehicle applications. Others, like CEREBRUMX, Motorq, and Smartcar, have been built specifically to turn OEM-generated data into scalable, hardware-free services for insurers, fleets, and developers. What links them is a shared focus on reducing integration complexity, expanding the range of monetizable use cases, and building recurring revenue from data that vehicles already generate.
The market's 17.9% CAGR through 2031 reflects how early the commercial infrastructure still is relative to the volume of data being produced. Predictive maintenance, usage-based insurance, fleet optimization, and EV charging management are already established revenue streams. Newer applications — in-vehicle commerce, smart city intelligence, autonomous vehicle development data, and road health monitoring — are still maturing. As regulatory frameworks stabilize across regions and data standardization improves, the companies that have built the deepest OEM relationships and the most flexible API and AI infrastructure are positioned to capture a disproportionate share of that growth.
Learn More and Take Action:
Consider becoming a member of the BCC Research library and gain access to our full catalog of market research reports in your industry. Not seeing what you are looking for? We offer custom solutions too, including our new product line: Custom Intelligence Services.